


By Andrew Oladokun | Softcanada Contributor Inflation is up, jobs are down, and on Wednesday the Bank of Canada must choose. Here’s what its decision means for your wallet.

On Wednesday, October 28, at 9:45 a.m. Eastern, a small group of people in Ottawa will announce one number. That number will quietly ripple through credit card statements, car loans, mortgage plans and maybe even job offers across the country.
It’s the Bank of Canada’s interest rate decision. If you’re new to Canada, or about to be, here’s why you should care, without the economics degree.
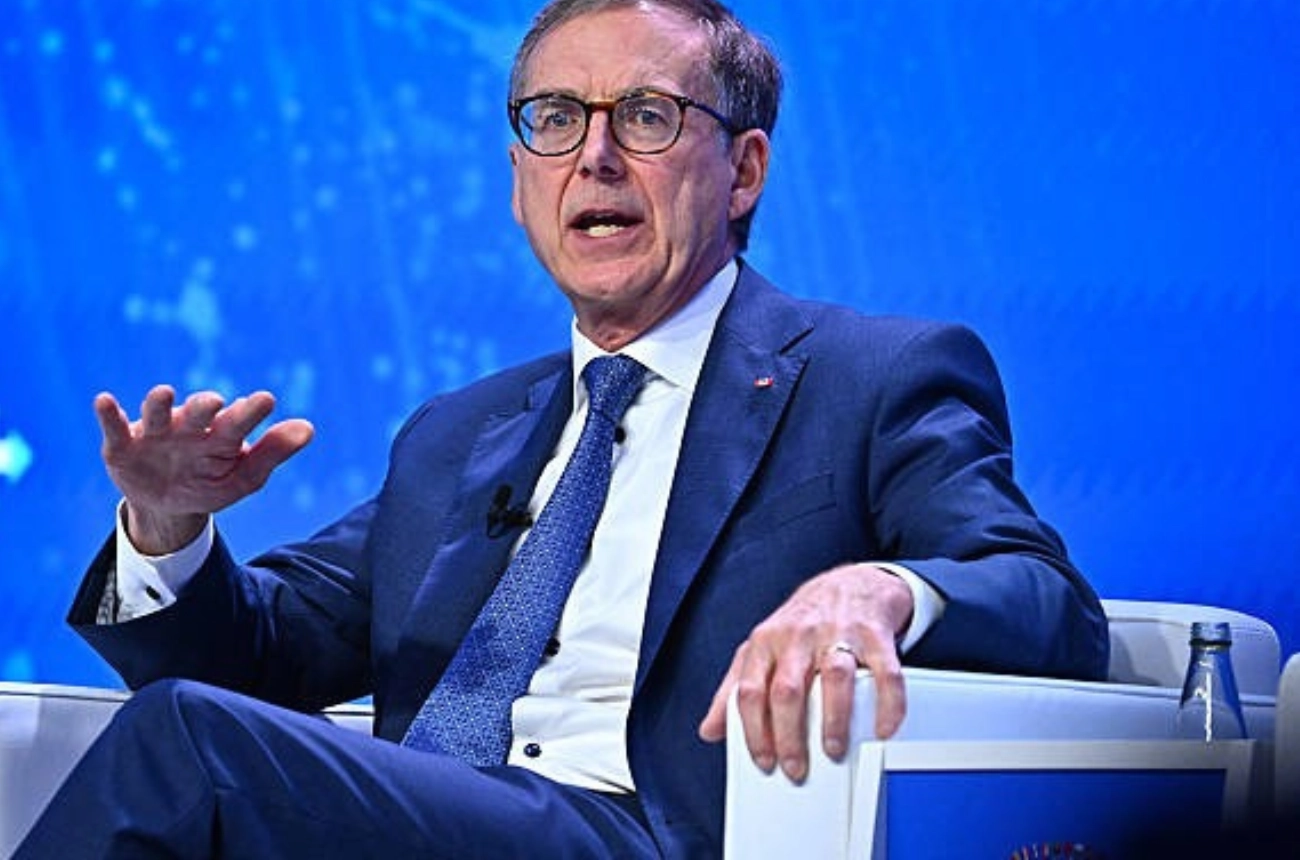
The Bank of Canada sets a key interest rate, called the policy rate. Right now it sits at 2.25%. Banks use it as a reference for what they charge you to borrow.
Think of it as the thermostat for Canada’s economy. Turn it up, and borrowing gets more expensive, spending cools and inflation should ease. Turn it down, and borrowing gets cheaper and spending warms up.
The Bank is stuck between two bad headlines.
On one side, prices are rising. Inflation climbed to 3.1% in September, above the Bank’s 2% target. The big culprit was gasoline, up 27.8% from a year earlier. Strip out gas, and inflation was a calmer 2.2%. On the other side, jobs are falling. Canada lost 68,000 jobs in September, and the unemployment rate rose to 6.5%. Raise rates to fight inflation, and you risk hurting a shaky job market. Hold rates to protect jobs, and you risk prices running hotter. Economists can’t agree: markets were pricing in roughly an 80% chance of a quarter-point hike, while RBC expects the Bank to hold through the rest of the year.
In other words, nobody knows. Which is exactly why everyone is watching.
If the Bank raises its rate, the effects show up fast. Variable-rate loans and lines of credit get pricier almost immediately, and future mortgages could cost more, which stings if you’re saving for your first Canadian home. The small silver lining is that savings accounts may pay a little more interest. If the Bank holds instead, borrowing costs stay roughly where they are, and an already shaky job market avoids an extra squeeze from higher rates. But one thing won’t change whatever Ottawa decides: standard credit cards often charge around 20% interest, so carrying a balance stays expensive either way.
This is the part newcomers often miss. Higher interest rates tend to slow hiring, because businesses borrow less and expand more cautiously. With unemployment already at 6.5%, a hike could make the job hunt tougher in the months ahead.
If you’re planning to move soon, build a bigger savings cushion and give yourself more time to land work.
Wednesday’s decision will be made by economists, but it will be felt at kitchen tables. Whether the Bank raises or holds, the smart newcomer move is the same: borrow carefully, save steadily and keep your options open.
We’ll be back after the announcement with what actually happened, and what it means for you.
SoftCanada does not assume responsibility for content published on external websites or sourced from third parties.


Rent Is Finally Coming Down in Some Canadian Cities. Should Newcomers Be Excited?
Canada vs. the United States: Where Is It Easier for an Immigrant to Build a Life? — Part 2
Fonthill Welcomes Fountain Veritas Medical Centre
Inside the Expedier Business Gala: A Room Full of Business Owners and a Platform Ready to Back Them
A New Governor Takes the Helm: Uche Okugo Installed as District Governor of Rotary International District 7080
Built on Belief and Backed by Great Deals: Soft Canada Auctions Launches to make winners every week.
How to Survive Your First Winter Without Overspending
The Truth About Loneliness Among New Immigrants in Canada
BISC MedSpa & Cosmetics Opens Its Doors in Etobicoke — Beauty Gets a New Home in Toronto
Why Many Newcomers Are Leaving Toronto and Vancouver for Smaller Cities