


New to Canada with no credit history? Learn how to build your credit score, improve your rental prospects, qualify for credit cards, and secure your first apartment. By CanadaSoft

You’ve landed in Canada. You have savings,a job offer and a spotless record back home. Then a landlord asks for yourcredit score, and suddenly you’re a ghost.
It’s not personal. Canada justdoesn’t know you yet. Your credit history from home usually doesn’t follow you,so most newcomers start from zero. Here’s how to go from “who?” to “approved.”
First,what is a credit score?
It’s a three-digit number between300 and 900 that tells lenders how risky it is to lend you money. The higher,the better. According to Equifax, a score of 660 or above is generallyconsidered good.
Canada has two main credit bureaus,Equifax and TransUnion. They collect information from banks, card companies andother lenders, then turn your borrowing habits into a score.
And it’s not just banks that check.Landlords, mobile phone companies and insurers may look at your credit too.That’s why it matters from week one.
Step1: Open a bank account right away
Most major Canadian banks offernewcomer packages, often with reduced fees and a starter credit card, even withoutCanadian credit history. Bring your passport and immigration documents, and askspecifically about newcomer offers.
Step2: Get a credit card, even a small one
This is the engine of your score. Ifyou can’t get a regular card, ask for a secured credit card. You put down adeposit, say $500, and that becomes your credit limit. It works like a normalcard, and your payments are reported to the bureaus.
Think of it as training wheels.You’ll graduate soon.
Step3: Pay on time. Every time.
Your payment history carries themost weight in your score. Equifax estimates it at about 35%.
One late payment can sting foryears, so set up automatic payments for at least the minimum amount. Betterstill, pay the full balance every month. You avoid interest, and your scoreclimbs.
Step4: Don’t max it out
Here’s the twist: using your wholecredit limit hurts your score, even if you pay it off.
The Government of Canada recommendsusing 35% or less of your available credit. On a $1,000 limit, that meanskeeping your balance under $350. Use the card for small, regular purchases likegroceries or your phone bill, then pay it off.
Step5: Be patient and strategic
Credit is built over months, notdays. A few habits help:
Step6: Check your report
You can request your credit reportfrom Equifax and TransUnion, and several free apps let you track your score.Check it regularly for errors and signs of fraud. A mistake on your report candrag your score down, and you have the right to dispute it.
Whileyou build: the apartment problem
No score yet, but you need a homenow? Landlords may accept alternatives: a larger deposit where provincial rulesallow, a letter from your employer, proof of savings, or a co-signer. Beupfront that you’re new to Canada. Many landlords have seen it before.
Thebottom line
In Canada, a good credit score isn’tabout being rich. It’s about being consistent. Open the account, get the card,pay on time, keep your balance low, and let time do the rest.
Give it a year, and the ghostbecomes a tenant.
SoftCanada does not assume responsibility for content published on external websites or sourced from third parties.


Rent Is Finally Coming Down in Some Canadian Cities. Should Newcomers Be Excited?
Canada vs. the United States: Where Is It Easier for an Immigrant to Build a Life? — Part 2
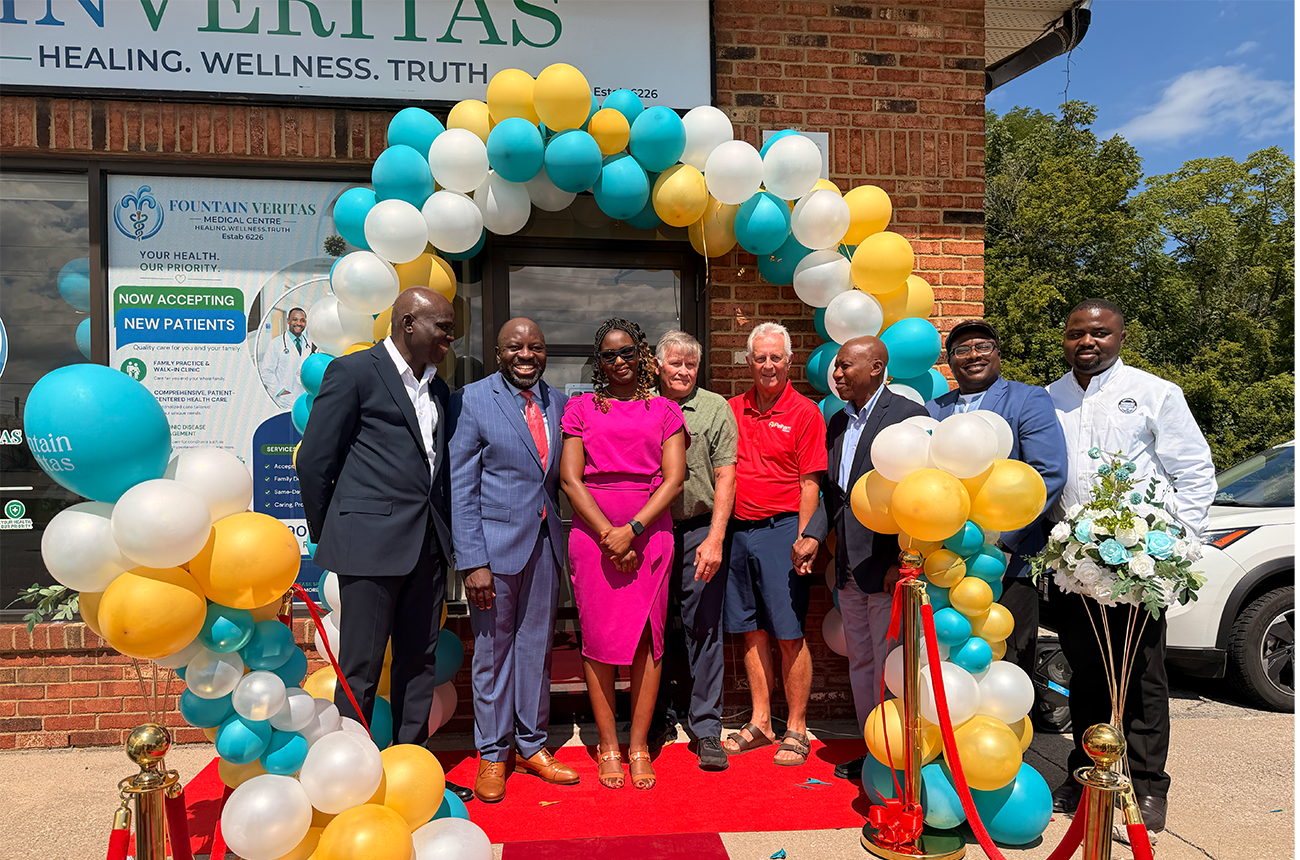
Fonthill Welcomes Fountain Veritas Medical Centre
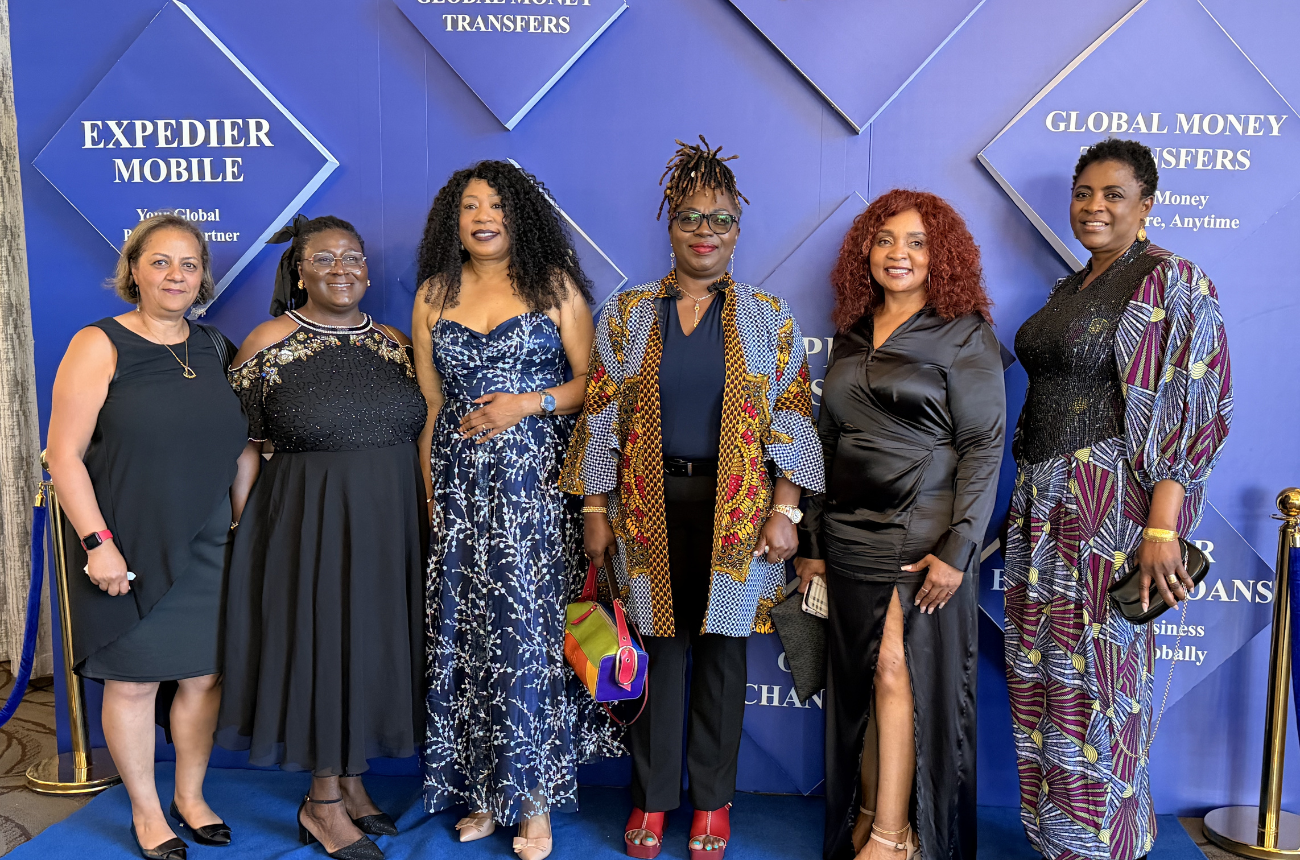
Inside the Expedier Business Gala: A Room Full of Business Owners and a Platform Ready to Back Them
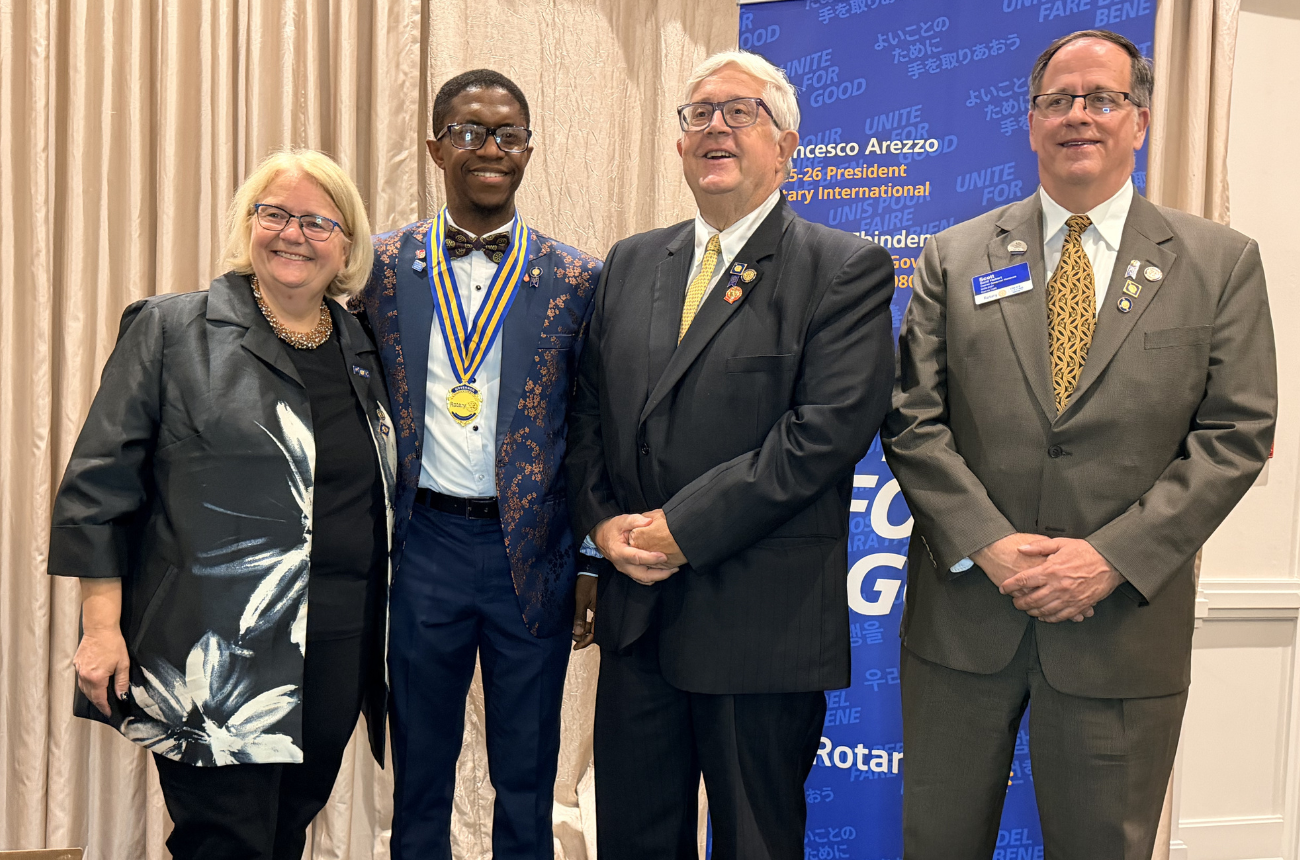
A New Governor Takes the Helm: Uche Okugo Installed as District Governor of Rotary International District 7080
Built on Belief and Backed by Great Deals: Soft Canada Auctions Launches to make winners every week.
How to Survive Your First Winter Without Overspending
The Truth About Loneliness Among New Immigrants in Canada
BISC MedSpa & Cosmetics Opens Its Doors in Etobicoke — Beauty Gets a New Home in Toronto
Why Many Newcomers Are Leaving Toronto and Vancouver for Smaller Cities